Independent valuation
We act as independent valuer and issue a signed, formal valuation report, for transactions, financial reporting and other purposes where an independent opinion is needed.
Every engagement is led personally by a senior member of our team, from the first call to completion. You deal with one senior person who knows your business, not a rotating team.
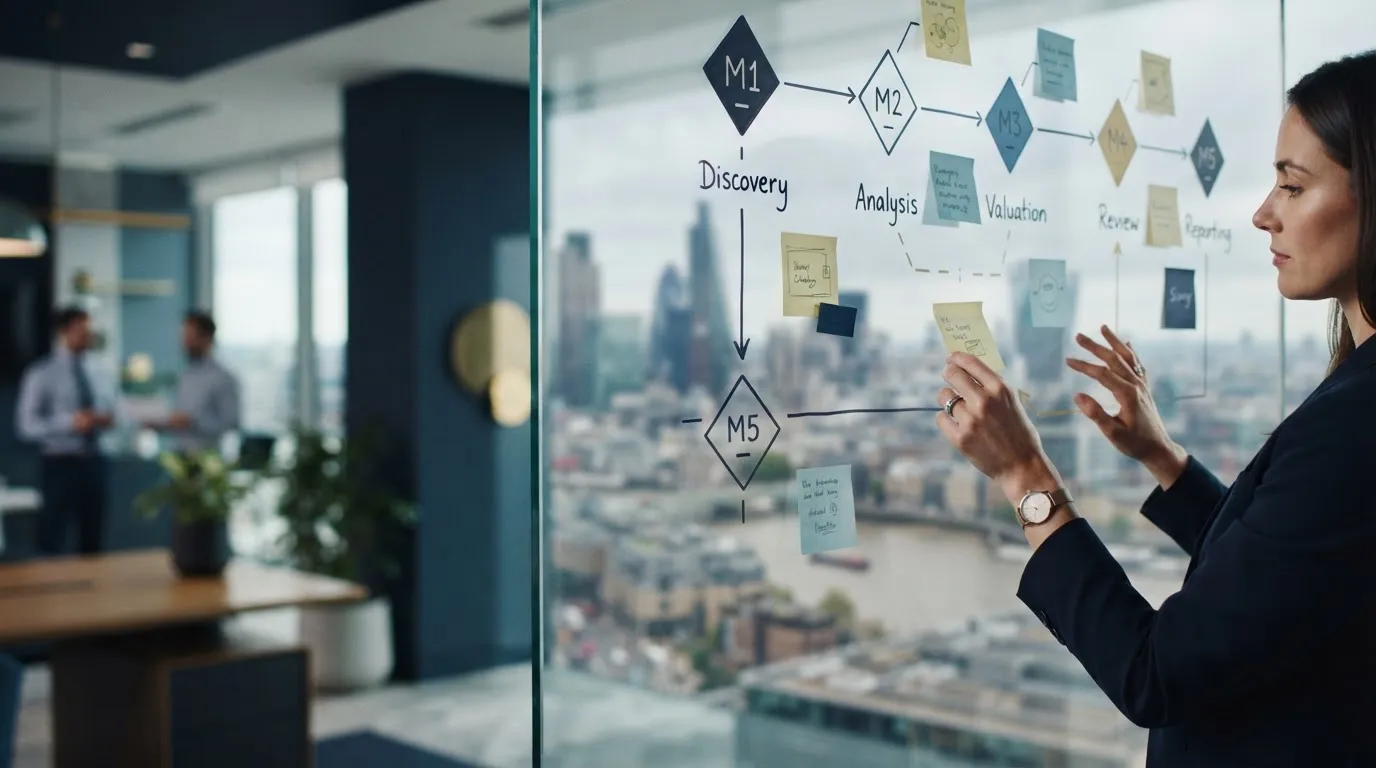
A call to understand the purpose of the valuation, the valuation date, your deadline and who will rely on the report, such as investors, auditors or regulators. We then send a proposal tailored to your needs and how involved you'd like us to be.
A short, tailored list of what we need, typically historical financials, management projections, the cap table and key agreements. We keep requests focused so your team isn't buried in paperwork.
A working session with management on the business model, the market, competitors and the key value drivers. This is where most of the value of our work is created.
We test the projections, research the industry, select the right valuation approaches and cross-check the results. Key judgements are documented as we go, ready for review.
We walk you through the draft conclusions and the key assumptions before anything is finalised, so there are no surprises.
A clear report setting out key judgements, input sources and cross-checks.
We respond promptly to queries from the relevant parties until the valuation is signed off.
Every proposal is tailored to what you need and how involved you would like us to be. Options range from:

We act as independent valuer and issue a signed, formal valuation report, for transactions, financial reporting and other purposes where an independent opinion is needed.
We work alongside your team and prepare unbranded valuation exhibits for your internal use and reference.
We train your finance or valuation team to carry out the valuation themselves, covering the methodology, the key judgements and what reviewers will look for.
Common triggers include raising capital, selling or buying a business or a stake, granting share-based compensation such as share options or restricted share awards, completing an acquisition (purchase price allocation), annual impairment testing, reporting fund investments at fair value, and certain tax and restructuring events.
An indicative valuation gives an early, realistic range based on a lighter scope of work. It helps you decide whether and when to pursue a deal. A full valuation involves more analysis, including stress-testing the projections, benchmarking against peers, industry research and scenario analysis, to narrow the range into a value you can rely on in negotiations or reporting.
Typically, two to three years of financial statements, management accounts for the current year, financial projections, the cap table and the key agreements relevant to the valuation. We send a tailored request after the scoping call, so you only provide what's needed.
Timing depends on the type of valuation and how quickly complete information is available. Indicative valuations can take 2–3 weeks, while purchase price allocations typically take 4–6 weeks.
No. You can choose the level of support you need. If you don't need a formal valuation report, we can work alongside your team as management's expert and prepare unbranded valuation exhibits for your internal use. We can also train your finance or valuation team to carry out the valuation themselves. On the scoping call, we'll help you decide which option fits your purpose.
Our approach and documentation are designed for audit review. We follow International Valuation Standards and the relevant financial reporting standards, and we know from experience what Big 4 and mid-tier reviewers look for. We disclose our methodology and calculations in full, and are happy to agree the approach with your auditors before work starts. Auditors form their own independent view, so no valuer can guarantee acceptance, but we work to make the review as smooth as possible and respond to their questions directly.
There is no fixed cut-off. Auditors will generally expect your investment to be marked to the most recent round, adjusted for terms such as liquidation preferences, the size of the round and who invested. But a round becomes weaker evidence of fair value the longer ago it took place and the more has changed since. A missed forecast, a change in business model, a down round among comparable companies or a sharp market move are all signs that the round may be stale and a fresh valuation is needed. We can help you assess at each reporting date whether the round still holds.
Yes. We handle all client information in confidence and in line with Singapore's Personal Data Protection Act (PDPA), and we are happy to sign a non-disclosure agreement before you share anything.
No. We are based in Singapore and have valued businesses across Southeast Asia, Greater China, India, Australia, the US and Europe.